Best Money Apps in 2026: How to Pick the Right One for You
Choosing among the best money apps in 2026 can feel overwhelming when every platform promises to save you time and money. The truth is that no single app wins for everyone. The smart move is matching an app’s strengths to how you actually spend, save, and send. This guide compares the leading options and gives you a clear framework for deciding.
Money apps have quietly reshaped daily life. A generation ago, splitting rent meant writing a check; today it means tapping a screen. But with dozens of competitors chasing your attention, understanding the real differences between them is what separates a confident user from a confused one.
What makes a money app worth downloading?
Not all financial tools deserve space on your phone. The best money apps share a handful of qualities that make them genuinely useful rather than just another icon collecting dust. Before installing anything, weigh these factors.
- Low or transparent fees so convenience does not quietly drain your balance.
- Strong security, including encryption, biometrics, and fraud alerts.
- Broad acceptance among the people and merchants you deal with.
- Extra features like budgeting, investing, or cash-back rewards.
- Reliable support when something inevitably goes wrong.
Comparing the top money apps side by side
Each major platform has a personality. Some excel at instant peer transfers, others at investing or budgeting. The table below distills what each does best so you can spot your ideal match quickly.
| App | Best For | Standout Feature | Watch Out For |
|---|---|---|---|
| Cash App | Fast P2P transfers | Cash Card + Bitcoin investing | Instant-transfer fees |
| Venmo | Social payments | Public payment feed | Privacy defaults |
| PayPal | Online shopping | Buyer protection | Higher merchant fees |
| Zelle | Bank-to-bank sends | No app-held balance | Hard to reverse |
| Chime | Everyday banking | Early direct deposit | Limited branch access |
For anyone leaning toward peer-to-peer transfers, our in-depth Cash App guide walks through setup, fees, and safety in plain language. Reading a focused breakdown beats guessing from app-store screenshots.
Which money app is safest?
Safety often decides which app people trust with their paychecks. Look for services whose partner banks provide FDIC insurance and whose apps require biometric login. The FDIC consumer resources explain how deposit insurance protects your money when it sits with an insured institution, a detail worth confirming before parking a large balance anywhere.
Remember that most fraud happens through deception, not hacking. Scammers impersonate support agents or post fake “too good to be true” deals. No legitimate money app will ever ask for your PIN or one-time code, so treat any such request as an instant red flag.
Security habits that apply to every app
- Turn on two-factor authentication the moment you sign up.
- Use a unique password not shared with your email or bank.
- Review transaction alerts daily and report anything odd fast.
- Never send money to strangers promising to multiply it.
How to choose the right app for your life
Start with your dominant use case. If you mostly split costs with friends, prioritize a strong peer-to-peer network. If you shop online constantly, buyer protection matters more. If you are building savings habits, an app with budgeting and early-deposit features earns its place.
Many people end up using two apps: one for social transfers and one for banking or investing. That is perfectly fine, provided you keep track of balances and avoid scattering your money so widely that you lose sight of it. Comparing several best money apps before committing helps you avoid buyer’s remorse.
A quick decision checklist
- Who do I send money to most, and what do they use?
- Do I need investing, budgeting, or just transfers?
- Am I comfortable with the fee structure long term?
- Does the app offer insurance and strong security?
Managing money well is a lot like managing a home project: the right specialists make everything smoother. When budgeting for a big upgrade, coordinating with reputable service experts keeps your spending planned and your payment schedule clear from start to finish.
Matching an app to your spending personality
Money apps are not one-size-fits-all, and your temperament matters as much as the feature list. If you are a spender who struggles with impulse purchases, an app with strict budgeting alerts and savings locks will serve you far better than one built purely for fast transfers. If you are a natural saver, an investing-focused platform may unlock more growth.
Consider how you react to notifications, too. Some people thrive on constant balance alerts; others find them stressful and start ignoring the app entirely. The best money apps let you tune these settings, so test the defaults during your first week and adjust until the experience feels supportive rather than nagging.
Frequency of use is another factor. A tool you open daily should be fast and uncluttered, while an app you check monthly can afford richer dashboards and deeper reports. Honest self-assessment here prevents the common mistake of downloading a powerful platform you never actually open.
The rise of all-in-one financial apps
A defining trend in 2026 is consolidation. Apps that once did one thing now bundle spending, saving, investing, and even tax tools into a single dashboard. This convenience is appealing, but it also concentrates risk, so choose consolidated platforms only when their security and support genuinely earn your trust.
The upside is real: fewer logins, unified statements, and smarter insights drawn from your complete financial picture. The best money apps use that data to nudge you toward better habits rather than simply upselling you on new products.
Before going all-in on a single super-app, weigh the convenience against concentration risk. Keeping a backup transfer method on a second platform means one outage or frozen account never leaves you completely stranded, a small insurance policy that costs nothing to set up.
Frequently Asked Questions
Can I use more than one money app at once?
Absolutely. Many people pair a peer-to-peer app for friends with a banking app for deposits. Just monitor each balance so funds do not sit forgotten.
Are money apps free to use?
Core transfers are usually free. Fees appear for instant withdrawals, credit-card funding, or premium features, so read the fee schedule before relying on any app.
What is the safest way to receive money from strangers?
Prefer apps with buyer or seller protection for transactions with people you do not know, and never share verification codes with anyone.
Do money apps help with budgeting?
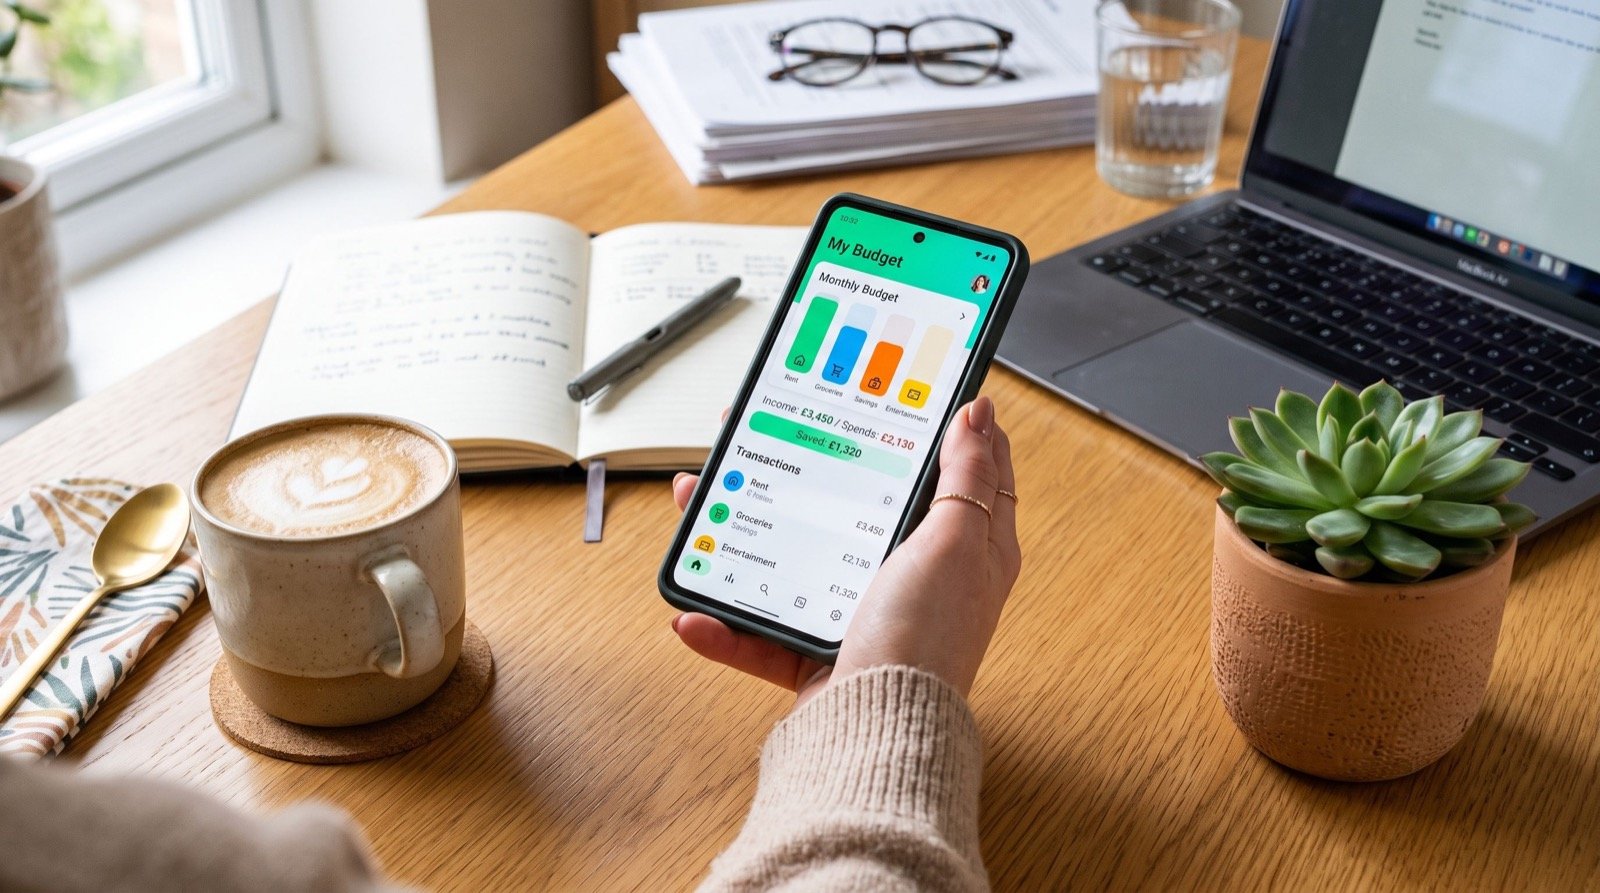
Many now include spending categories, savings goals, and alerts. These tools give a clear snapshot of where your money goes each month.
Final takeaway
The best money apps in 2026 are the ones that fit your habits, protect your funds, and keep fees transparent. Match features to your real needs, layer on strong security, and do not be afraid to run two apps if that serves you better. Choose deliberately, and your phone becomes a genuine ally in reaching your financial goals.